
The People Reading Your Application
Underwriters and advisors who pick up the phone — every file is decided by someone whose name you know.
The People Reading Your Application
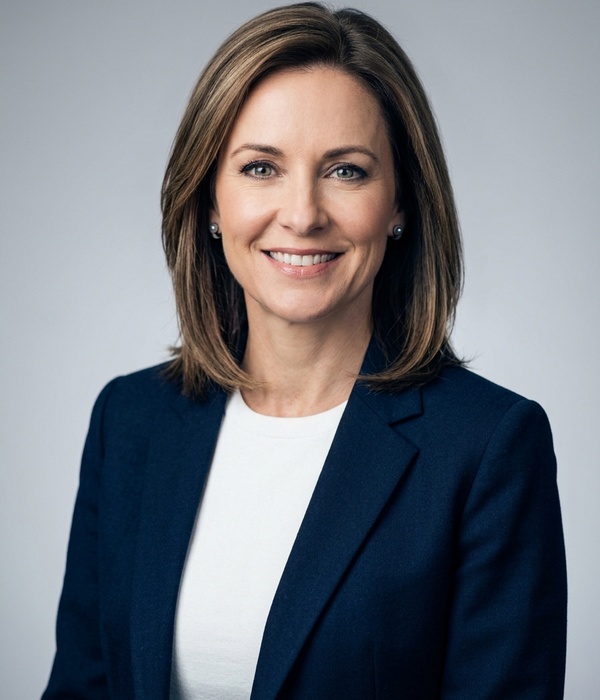
Hannah Reyes
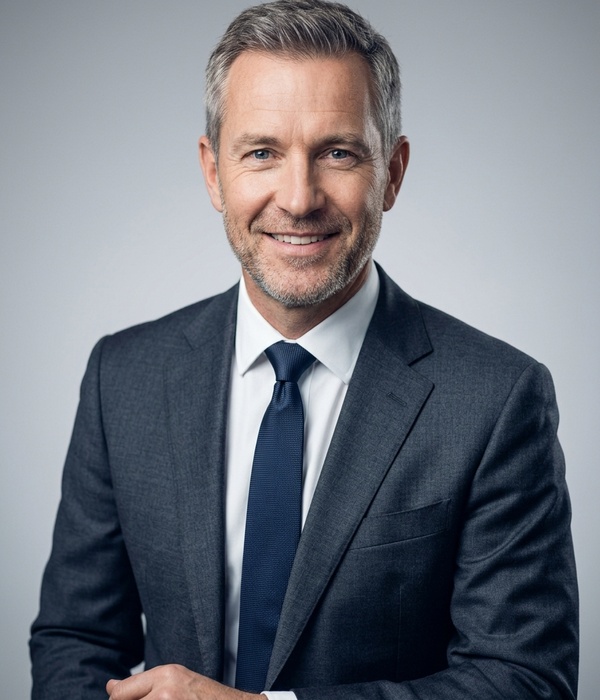
Marcus Bell
Sofia Grant
David Okafor
What Your Advisor Actually Does
Your Mortgage, Project-managed
From offer to keys, one advisor owns your file — they chase the valuer, the solicitor and the underwriter so you never have to.
Document review
Statements checked before submission — no bounce-backs.
Rate strategy
Fixed vs tracker modelled against your plans, in numbers.
Closing coordination
Valuation, legal and lender milestones tracked for you.
Post-completion care
Rate-drop alerts and remortgage reviews every year.
A Lender Who Reads Your P&L
Your advisor models repayments against seasonality and cash-flow so the loan fits the business — not the other way round.
Cash-flow fit
Repayment sized to your quiet months, not your best ones.
Structure advice
Term loan, credit line or both — costed side by side.
Clean documentation
One checklist, one upload — approval-ready first time.
Growth reviews
Quarterly check-ins to re-price as your revenue grows.
Borrow Less, Smarter
Our advisors are paid on service scores, not loan size — so the plan you get is the cheapest way to your goal, even when that means borrowing less.
True-cost modelling
Every option shown with total interest, not just the monthly.
Consolidation math
Your cards and loans folded into one payment — only if it saves.
Score protection
Soft searches throughout — your file stays clean.
Payoff planning
An overpayment plan that cuts months off the term.
Pay Less For Money You Already Borrowed
We re-shop your existing loans against today’s rates. If switching saves less than the fees cost, we tell you to stay put — in writing.
Break-even analysis
Exact month your switch starts saving real money.
Balance transfers
High-APR card debt moved to one fixed payment.
Term redesign
Shorter term, same monthly — when rates allow it.
Fee transparency
Every switching cost listed before you commit.
Drive Away Without Dealer Markup
Pre-approved funds before you walk into the showroom — so you negotiate like a cash buyer and the finance desk can’t pad your rate.
Pre-approval first
Walk in with funds agreed — negotiate the price, not the payment.
New, used or private
Dealer lots, auctions or a private sale — same rate either way.
Total-cost view
Insurance, registration and interest modelled before you commit.
Trade-in bridging
A short bridge covers the gap while your old car sells.
Fund The Degree, Defer The Payments
Nothing to repay until six months after graduation — your advisor structures the loan around semesters, co-signers and scholarships.
Semester drawdowns
Funds released per term, so interest only accrues on what you use.
Co-signer planning
A co-signer cuts your rate by about 1% — released after 24 clean payments.
Autopay discount
0.25% off your APR with automatic repayments.
Grace-period coach
A repayment plan ready before your first bill arrives.
Five Payments In, One Payment Out
We fold cards, overdrafts and store credit into a single fixed payment — and only recommend it when the math actually saves you money.
One fixed payment
Every balance folded into a single date, rate and direct debit.
True-saving check
Total interest before vs after — in writing, before you sign.
Score protection
Soft searches while we plan; one hard check only when you accept.
Habit dashboard
Your dashboard tracks the payoff and flags creep before it grows.
Funded And Vouched For
“Applied on Tuesday morning, signed after lunch and the money was in our account on Thursday. Our espresso machine died on Monday — we never closed a single day.”

“The calculator showed me exactly what consolidating would cost before I even applied. My five cards became one payment — $214 less every month.”

“A real person called within the hour to walk through my numbers. Our first warehouse is stocked, staffed and shipping — six weeks after that call.”

“I overpaid for two years with no penalty and cleared the loan 14 months early. The dashboard showed the interest saved in real time — addictive stuff.”

Ready To Fund Your Next Move?
Check your rate in two minutes — it will not affect your credit score.